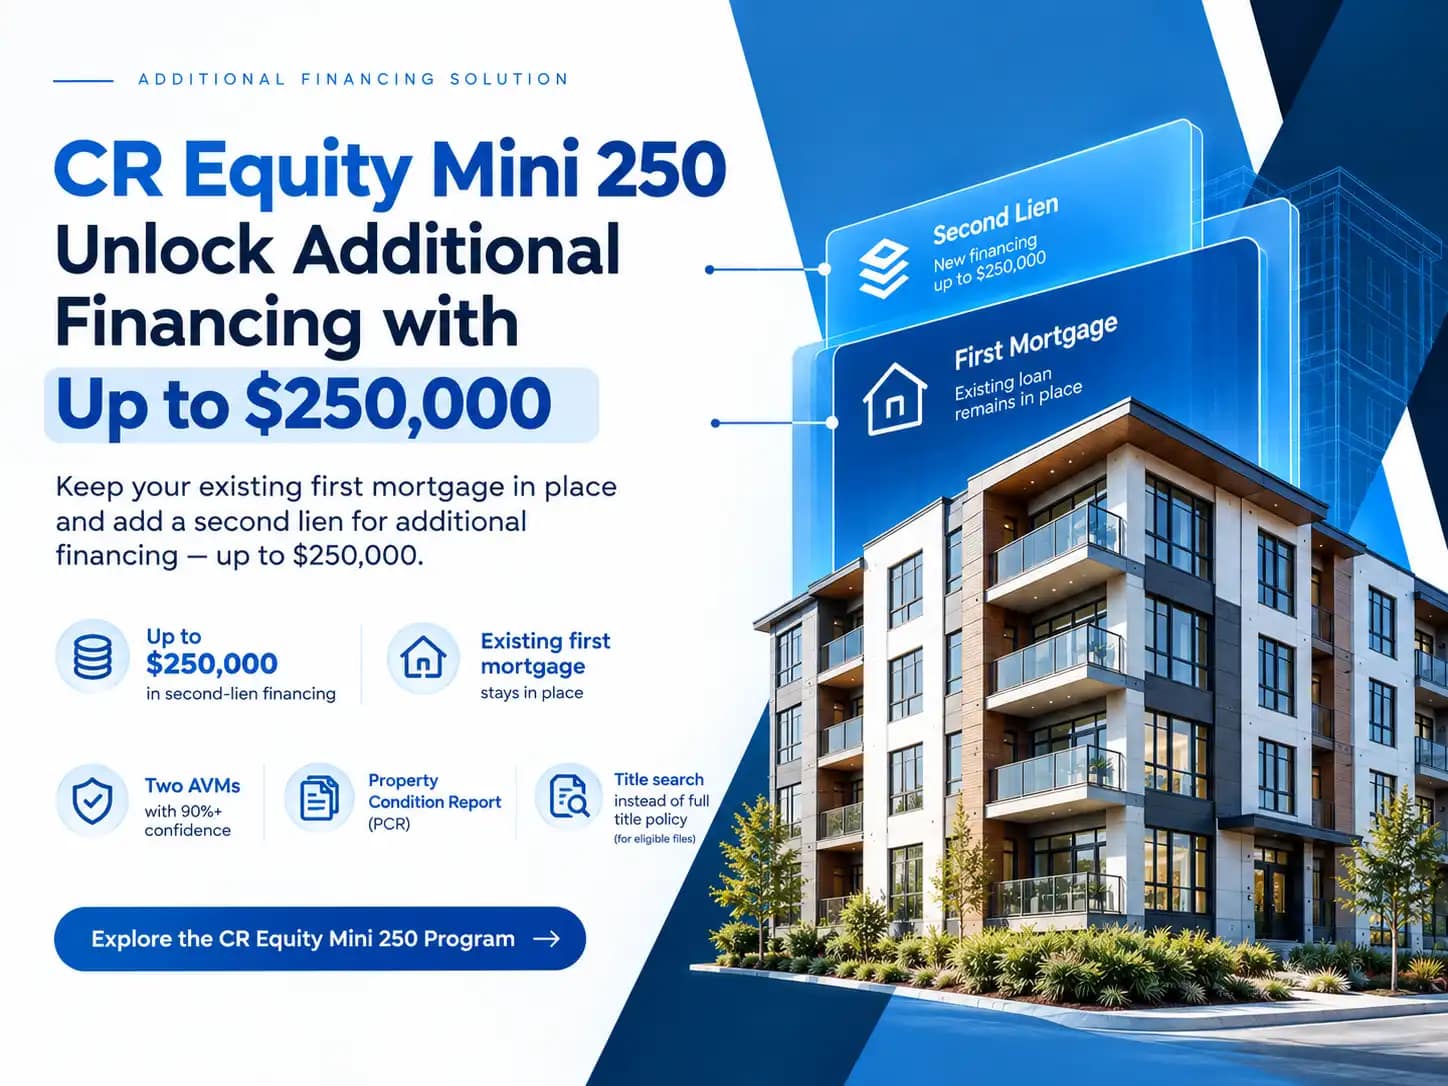
CR Equity AI has launched CR Equity Mini 250, a new financing program for eligible Non-QM second liens up to $250,000.
The program is designed for borrowers who want additional financing while keeping their existing first mortgage in place.
A second lien is different from a refinance: the existing first mortgage is not paid off. Instead, the new CR Equity AI loan is placed behind it in second lien position.
What’s new with CR Equity Mini 250?
CR Equity Mini 250 provides an additional financing option for eligible Non-QM second liens with a maximum loan amount of $250,000.
The program also introduces a streamlined valuation and title process for qualifying transactions:
- Up to $250,000 in second-lien financing
- Existing first mortgage stays in place
- Two AVMs with at least 90% confidence
- Property Condition Report (PCR)
- Title search instead of a full title policy for eligible files
- Property ownership or vesting must remain unchanged
- Closing coordinated through CR Equity AI’s applicable notary or attorney network
Program terms and final approval remain subject to underwriting and eligibility requirements.
What is CR Equity Mini 250?
CR Equity Mini 250 is CR Equity AI’s Non-QM second lien financing program for eligible loans of $250,000 or less.
A second lien is an additional loan secured by a property that already has a first mortgage.
The existing first mortgage remains in first position. The new CR Equity Mini 250 loan becomes the second lien.
For example:
Existing first mortgage: remains in place
New CR Equity Mini 250 financing: second lien
Maximum program amount: $250,000
This structure gives an eligible borrower another financing option without making the new transaction a refinance of the existing mortgage.
CR Equity Mini 250 vs. refinance
The distinction is straightforward.
A refinance replaces the existing mortgage.
CR Equity Mini 250 keeps the existing first mortgage in place and adds another loan behind it.
| Refinance | CR Equity Mini 250 | |
|---|---|---|
| Existing first mortgage | Paid off and replaced | Stays in place |
| New loan position | First lien | Second lien |
| Existing loan | Replaced | Remains |
| Purpose | Replace current financing | Add financing without paying off the first mortgage |
| CR Equity AI option | DSCR refinance | CR Equity Mini 250 |
For borrowers who want to replace the current mortgage, CR Equity AI’s DSCR refinance program is a different product.
A streamlined valuation process for CR Equity Mini 250
One of the key features of CR Equity Mini 250 is its valuation process.
Eligible second-lien files use:
Two AVMs
Each Automated Valuation Model must meet the program’s 90%+ confidence requirement.
Property Condition Report
A Property Condition Report (PCR) is also required.
Together, the two AVMs and PCR provide the valuation information for eligible files instead of a traditional appraisal.
This does not mean the property is evaluated without a valuation. It means the eligible transaction uses a different valuation process.
CR Equity AI also charges a $999 AIVAA™ fee for this program. AIVAA — AI Valuation & Analytics Assessment — is a property evaluation and is not an underwriting or loan-decision engine.
A streamlined title process
Eligible CR Equity Mini 250 files can use a title search instead of a full title policy when property ownership remains unchanged.
A title search is still required.
The distinction is important:
Eligible file: title search, no full title policy under the streamlined process.
Ownership change required: the transaction follows the standard full title process.
This requirement should be identified early in the transaction.
Who can submit CR Equity Mini 250?
The program is available for eligible files submitted through CR Equity AI’s broker or correspondent channel.
The core requirements include:
- Non-QM second-lien structure
- Loan amount of $250,000 or less
- Property ownership/vesting remains unchanged
- Submission through a CR Equity AI broker or correspondent channel
All loans remain subject to underwriting and applicable program requirements.
ITIN and foreign national are borrower types, not this loan type. Those borrowers should be evaluated under the applicable ITIN & foreign national loan program.
Why CR Equity Mini 250 matters for brokers and correspondents
A second lien creates a different financing path from a refinance.
For an eligible transaction, the broker or correspondent can submit a new loan while the borrower’s existing first mortgage remains in place.
CR Equity Mini 250 also provides a defined valuation and title process, with CR Equity AI coordinating the applicable title and closing workflow.
That means the product can be evaluated as its own loan structure rather than treated as a refinance scenario.
How CR Equity Mini 250 works
The process follows four basic steps:
1. Submit the loan
Submit an eligible CR Equity Mini 250 second lien through the CR Equity AI portal.
2. Review eligibility
The file is reviewed for the program’s eligibility requirements, including loan amount and unchanged vesting.
3. Complete valuation and title requirements
Eligible files use two AVMs plus a Property Condition Report. The title-search process is used when ownership remains unchanged.
4. Proceed to closing
CR Equity AI coordinates the applicable closing process through its notary or attorney network.
CR Equity Mini 250 amount and fees
The maximum loan amount for CR Equity Mini 250 is:
$250,000
The currently published program fees include:
- AIVAA: $999
- Dual signing: $125 when requested
- Application fee: not yet set
- State-specific settlement costs
- Applicable pass-through costs in non-attorney states
Potential borrower savings of up to $2,000 are not guaranteed and depend on the transaction and applicable costs.
For current state-by-state fees, see the CR Equity Mini 250 fee schedule.
CR Equity Mini 250: a new second-lien financing option
CR Equity Mini 250 gives eligible borrowers a way to add financing while keeping their existing first mortgage in place.
The program supports eligible Non-QM second liens up to $250,000, with two-AVM valuation plus PCR for eligible files and a streamlined title process when ownership remains unchanged.
Program terms are subject to underwriting, eligibility requirements, and change without notice.