
AI property valuation combines public records, MLS data, tax rolls, and photos to produce an instant value estimate with a confidence score attached to it. It works best for screening deals, monitoring portfolios, and supporting underwriting decisions before a human reviews the file. It is not a drop-in replacement for a formal appraisal on every asset, especially unique properties or thin data markets.
TL;DR:
- AI property valuation is most reliable for standard homes in active markets, with accuracy decreasing for unique or rural properties due to limited or outdated data.
- Confidence scores and evidence packages help determine when estimates can be trusted for underwriting or need human review, especially in volatile markets.
- Market shifts, sparse comps, outdated photos, or biased training data can significantly increase error rates, making regular validation essential.
- AI valuation supports pre-screening, bulk revaluations, and initial drafting but cannot replace licensed appraisals for official closings on complex or unique properties.
- Deployment should be staged, with careful back-testing, error analysis, and clear governance rules to avoid overreliance on estimates in high-stakes decisions.
Table of Contents
- How AI Property Valuation Actually Works
- How AI Valuation Compares With Traditional Appraisals
- Where AI Valuation Breaks Down
- How Lenders and Appraisers Actually Use This Today
- A Practical Checklist for Adopting AI Valuation
- Regulatory and Legal Considerations for AI Valuation
- Market Volatility and the Limits of Model Accuracy
- Where I Land on Adoption
- Get Faster Decisions With Valuation Built Into the Loan
- Sources
- FAQ
How AI Property Valuation Actually Works
Automated valuation models, or AVMs, ingest several categories of data before producing a number. The typical inputs include public property records, MLS listing and sale history, tax assessment data, building permits, geospatial layers, and photos from listings or inspections.
- Public records and tax assessments (ownership, lot size, prior sale price)
- MLS active and sold comps within a defined radius and time window
- Permit history (additions, renovations, code violations)
- Geospatial and neighborhood data, often pulled from open sources like OpenStreetMap
- Photos, used for condition scoring through computer vision
No single model handles all of that well on its own, which is why most serious platforms run an ensemble. An ensemble blends several statistical or machine learning models, then weights their outputs based on which one performs best for that property type and location. Enterprise AVM suites refresh their underlying data daily and combine multiple sub-models specifically to reduce the error rate across large, varied property sets, according to First American’s Procision AVM.
Computer vision adds a layer traditional statistical AVMs miss. A model trained on interior and exterior photos can flag deferred maintenance, upgraded finishes, or structural issues that pure comps-based math would never catch, closing the gap caused by assuming every home is in “average” condition, per Veros’s VeroVALUE Elite.
Statistic Callout: Professional-grade AVMs are built to output more than a single number. Expect a point estimate, a value range, a confidence score, and an evidence package documenting the comps and inputs used, a structure C3 AI’s property appraisal platform treats as standard for tools meant to plug into underwriting systems, as opposed to consumer-facing estimate tools built for general browsing.
How AI Valuation Compares With Traditional Appraisals
Speed is the most obvious gap. A licensed appraisal typically takes days to schedule, inspect, and write up. An AI valuation can return a point estimate and range in minutes, which matters when a fix-and-flip investor is deciding whether to make an offer before a competing buyer does.
Cost follows the same logic. Traditional appraisals carry inspection, travel, and report-writing overhead built into their fee. AI valuation strips most of that out, though the tradeoff is scope: a model estimates value, it does not certify it the way a licensed appraiser’s signature does.
- Speed: minutes versus days
- Cost: lower per-valuation cost, no scheduling delay
- Consistency: standardized comp selection removes appraiser-to-appraiser variance
- Scale: portfolio revaluation across hundreds of assets in a single batch run
Consistency is where AI tends to outperform on volume. Two human appraisers can select different comps for the same property and land on different values. A model applies the same comp-selection logic every time, which makes confidence scoring meaningful. That score tells an underwriter how much weight to put on the estimate before setting loan terms.
Pro Tip: Treat a high confidence score as a green light for automated underwriting rules, and treat a low one as an automatic trigger for human appraiser review, not as a number to override on judgment alone.
The strongest results come from hybrid workflows, where AI produces the first draft and a licensed appraiser signs off on anything that needs to hold up in front of a credit committee.
Where AI Valuation Breaks Down
Every model has failure modes, and knowing them matters more than knowing the average accuracy number. Unique properties, thin-inventory markets, and rapidly moving price environments all push AVM error rates higher than the reader might expect from marketing copy.
- Unique or non-conforming properties. A model trained on standard single-family comps struggles with a converted barn, a mixed-use building, or a home on a large irregular lot.
- Missing or outdated photos. Condition scoring only works if the model has current images. A listing with no interior photos forces the model to fall back on assumptions.
- Sparse comp data. Rural markets and low-turnover neighborhoods leave models with too few recent sales to anchor a confident estimate.
- Historical bias baked into training data. A model trained on decades of sales in a formerly redlined or underserved area can underweight recent improvements, since it is extrapolating from a skewed historical baseline.
- Rapid market moves. A model trained on trailing sales data lags a market that just repriced, whether up or down, in the last 60 to 90 days.
Confidence scoring exists precisely because no model is right every time. The discipline is not trusting the number. It is knowing when to stop trusting it and route the file to a human.
Privacy matters here too, especially regarding privacy, data governance, and compliance considerations in digital real estate workflows. Feeding third-party or crowd-sourced photos into a valuation model without clear consent mechanisms creates real exposure, a point vendor privacy frameworks like the Microsoft privacy statement address directly for any platform handling user-submitted images or data. Any adoption plan needs explicit escalation rules: below a defined confidence threshold, or above a certain loan-to-value exposure, the file goes to a licensed appraiser, no exceptions.
How Lenders and Appraisers Actually Use This Today
The use cases cluster around speed and scale rather than replacing judgment entirely. Underwriters use AI valuation as a pre-screen to kill or advance a deal before spending money on a full appraisal. Appraisers use AI-generated drafts as a starting point for commercial reports, then apply their own analysis to the parts that need a licensed signature. Portfolio managers run bulk revaluations across dozens or hundreds of holdings to catch value drift between full appraisal cycles.
- Underwriting pre-screens that filter deals before committing appraisal budget
- MAI-grade commercial valuation drafts that appraisers refine and sign
- Bulk portfolio revaluations for lenders monitoring existing collateral
- After-repair value (ARV) estimates for fix-and-flip underwriting
- Ongoing collateral monitoring between formal appraisal cycles
Pro Tip: Ask any AI valuation vendor for their evidence package format before you integrate. If they cannot show you the raw comps, model version, and confidence score behind a given output, you cannot defend that number in front of a credit committee later.
CR Equity Ai Inc’s own AIVAA valuation approach is built around that same principle: publishing advance-rate grids before an investor applies, so the underwriting logic behind a valuation is visible rather than a black box. Industry analysis increasingly frames AI as augmentation for appraisers rather than a replacement, automating the routine comp-pulling work so licensed professionals can spend their time on the exceptions that actually need judgment, per C3 AI’s property appraisal.
Operationally, the controls that matter most are embedding the evidence package directly into the loan file and setting credit committee review triggers tied to confidence score thresholds, so nothing above a defined risk level closes without a human sign-off.
A Practical Checklist for Adopting AI Valuation
Piloting an AI valuation tool without a validation plan is how false confidence creeps into a loan book. Run the model against deals you already know the outcome for before trusting it on new ones.
- Back-test against closed sales. Pull 50 to 100 recent closed transactions the model has not seen and compare its estimate to actual sale price.
- Calculate error bands. Look at P10 and P25 error metrics specifically, not just an average, since averages hide how bad the worst-case estimates get, a practice First American’s Procision AVM documentation recommends for validation.
- Check coverage gaps. Identify property types, ZIP codes, or price bands where the model has thin data and flag them for mandatory human review.
- Run sensitivity tests. Change one input at a time (comps radius, time window, condition score) and see how much the output moves.
- Decide integration architecture. API access suits high-volume, automated pipelines; a portal suits lower-volume manual review.
- Set governance rules. Define confidence thresholds that trigger appraiser escalation, and document vendor data-handling practices per resources like AICPA’s SOC guidance.
Statistic Callout: Enterprise deployments increasingly favor private-cloud or VPC-hosted AVMs with API-first integration specifically to keep borrower and comp data isolated from other tenants, according to AxcelerateAI’s real estate analysis. That architectural choice should factor into any vendor evaluation, not just the accuracy numbers on a sales deck.
Regulatory and Legal Considerations for AI Valuation
AI-generated valuations sit in a different legal category than licensed appraisals, and lenders need to know exactly where that line falls before relying on either one for a credit decision. A licensed appraiser’s signed report carries professional liability and state licensing requirements behind it. An AVM output, however sophisticated the model, does not carry that same certification, and using one in place of an appraisal where federal or state rules require a licensed appraisal creates compliance exposure.
Fair lending rules apply with equal force to AI-driven decisions. If a model’s training data reflects historical patterns tied to protected classes or redlined neighborhoods, its outputs can reproduce that bias even without anyone intending it to. Lenders using AI valuation as an input to credit decisions need to document how the model was validated for disparate impact, not just for average accuracy.
Data provenance is the other major exposure point. Third-party photos, crowd-sourced condition data, and consumer-submitted images all carry consent and usage restrictions that vary by source, which is why reviewing a vendor’s privacy statement, like the framework Microsoft publishes, belongs in any procurement checklist rather than an afterthought.
Maintaining an audit trail is the practical answer to most of this. A reproducible evidence package with raw inputs, model version, and confidence score preserves defensibility if a regulator or borrower ever challenges a valuation, a standard C3 AI’s platform builds around for exactly that reason.

Market Volatility and the Limits of Model Accuracy
AI valuation models are trained on historical sales data, which means every model has an inherent lag built into it. When a market shifts fast, whether from a rate move, a local employer layoff, or a sudden supply shock, the comps a model is drawing from reflect prices from before the shift happened.
This matters most for investors underwriting deals in volatile submarkets right now. A model that performed well in a stable rate environment can systematically overstate or understate value the moment the underlying market accelerates or contracts, since its training window has not caught up yet.
The practical fix is not abandoning the model. It is shortening the comp window during volatile periods and increasing the weight given to the most recent sales, while raising the confidence threshold required before a valuation gets automated underwriting treatment without human review. Lenders who monitor drift between model predictions and realized sale outcomes on a monthly basis catch this lag early, before it compounds across a portfolio.
Economic factors beyond price alone also affect reliability. Rising interest rates change buyer pools and time-on-market, both of which feed into comp selection logic. A model that does not adjust its comp weighting for time-on-market changes during a rate shock will keep leaning on comps that no longer represent current buyer behavior. That is a governance question as much as a technical one: someone on the underwriting team needs to own the decision of when to tighten the model’s inputs.
Where I Land on Adoption
Roll AI valuation out in stages, not all at once. Start with screening, where a wrong estimate costs you a passed-over deal rather than a bad loan. Move to underwriting support once you have back-tested the model against your own closed files. Expand further only after you have months of realized-sale data confirming the model holds up in your specific markets.
Keep a licensed appraiser in the loop permanently, not as a transition step you eventually phase out. The value of AI here is speed and consistency at scale, not judgment, and the two are not interchangeable. Firms that keep measuring model predictions against actual outcomes will be the ones still trusting their numbers in three years.
— Robert
Get Faster Decisions With Valuation Built Into the Loan
CR Equity Ai Inc pairs AIVAA property valuation directly with real capital, so an investor is not stuck holding a value estimate and then shopping it around to a separate lender. The platform lends its own funds, publishes advance-rate grids before you apply, and issues decisions in as little as four hours because the underwriting runs on the asset and the deal, not a stack of income documentation.
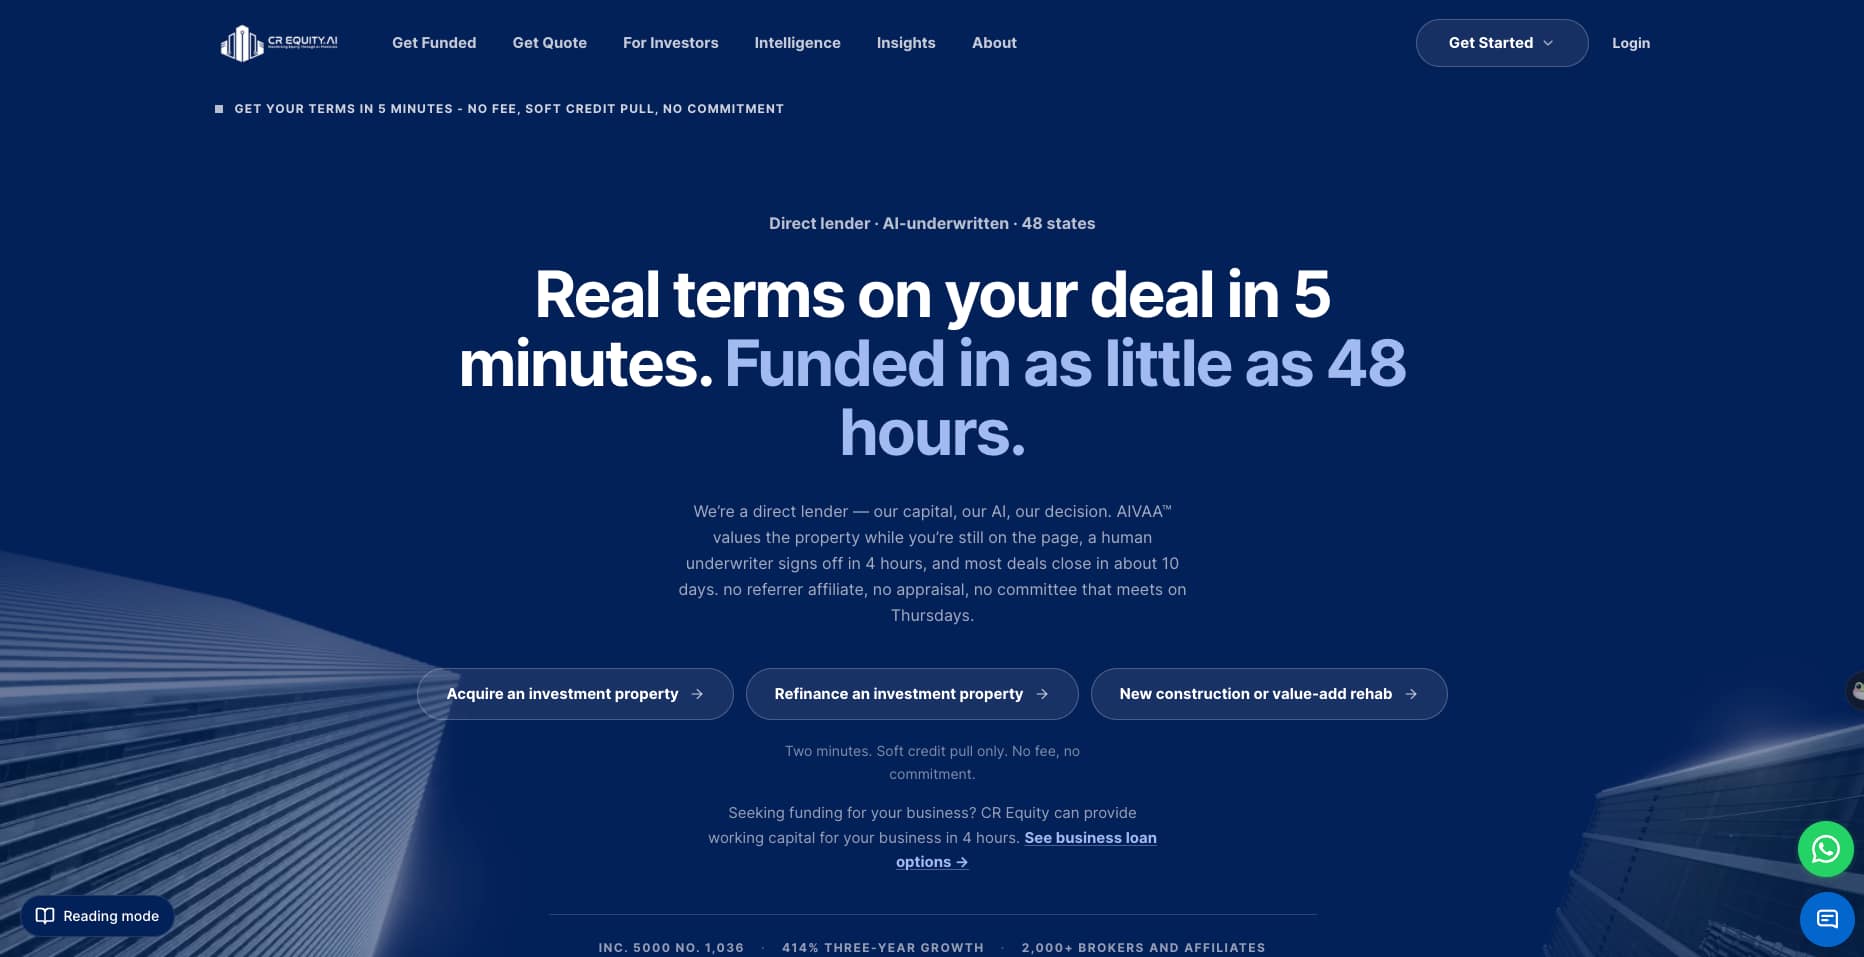
That structure fits specific jobs well: a fast pre-screen before you commit to a purchase, a defensible draft valuation to support an underwriting file, and capital delivery without waiting on a separate appraisal-then-financing sequence. Programs span investment property acquisition, fix-and-flip financing, and F.L.E.X. 50™ emergency bridge loans with published pricing and fees, funded in 24 to 48 hours for deals that cannot wait on a traditional timeline.
If you have a deal that needs a value estimate and a funding decision on the same clock, submit it directly and see the terms CR Equity Ai Inc can put in front of you.
Sources
FAQ
Can AI tell me what my house is worth?
AI can generate an instant estimate using public records, MLS data, and photos, along with a confidence score showing how reliable that estimate is likely to be. It is a strong starting point for screening or portfolio monitoring, but it is not a certified appraisal and should not replace one for loan closing where a licensed appraisal is required.
What is the 4-3-2-1 rule in real estate?
The 4-3-2-1 rule is not a recognized valuation or appraisal standard; definitions of it vary widely depending on the source, and it does not correspond to any established AVM or lending framework referenced in professional valuation practice.
What is the best app for finding property values?
Consumer-facing estimate tools are useful for general market awareness but are explicitly not appraisals, since they rely on public data without inspection or condition verification, as Zillow’s own Zestimate documentation states. For a valuation built to support an actual lending decision, look for a platform that pairs the estimate with an evidence package and a funding path, such as CR Equity Ai Inc’s AIVAA.
What is the best website to check property value?
There is no single best source, since accuracy depends heavily on local data coverage and comp density in your specific market. Cross-checking a consumer estimate against a professional-grade tool that shows its confidence score and evidence package, rather than a single unexplained number, gives a more defensible read.
How accurate is AI property valuation compared to a licensed appraisal?
Accuracy varies by property type and market data density, with standard single-family homes in active markets scoring highest and unique or rural properties scoring lowest. Professional AVMs address this by attaching a confidence score to every estimate, so the platform tells you when the number is reliable enough to act on versus when it needs human review, per C3 AI’s approach.