What to Expect From a Construction Draw Schedule Lender
CR Equity AI funds business-purpose real estate loans, and a construction draw schedule is the lender-approved plan for releasing loan funds as work is completed. You should expect construction funds to be released in stages, not all at closing. This structure helps keep loan proceeds tied to the approved project plan.
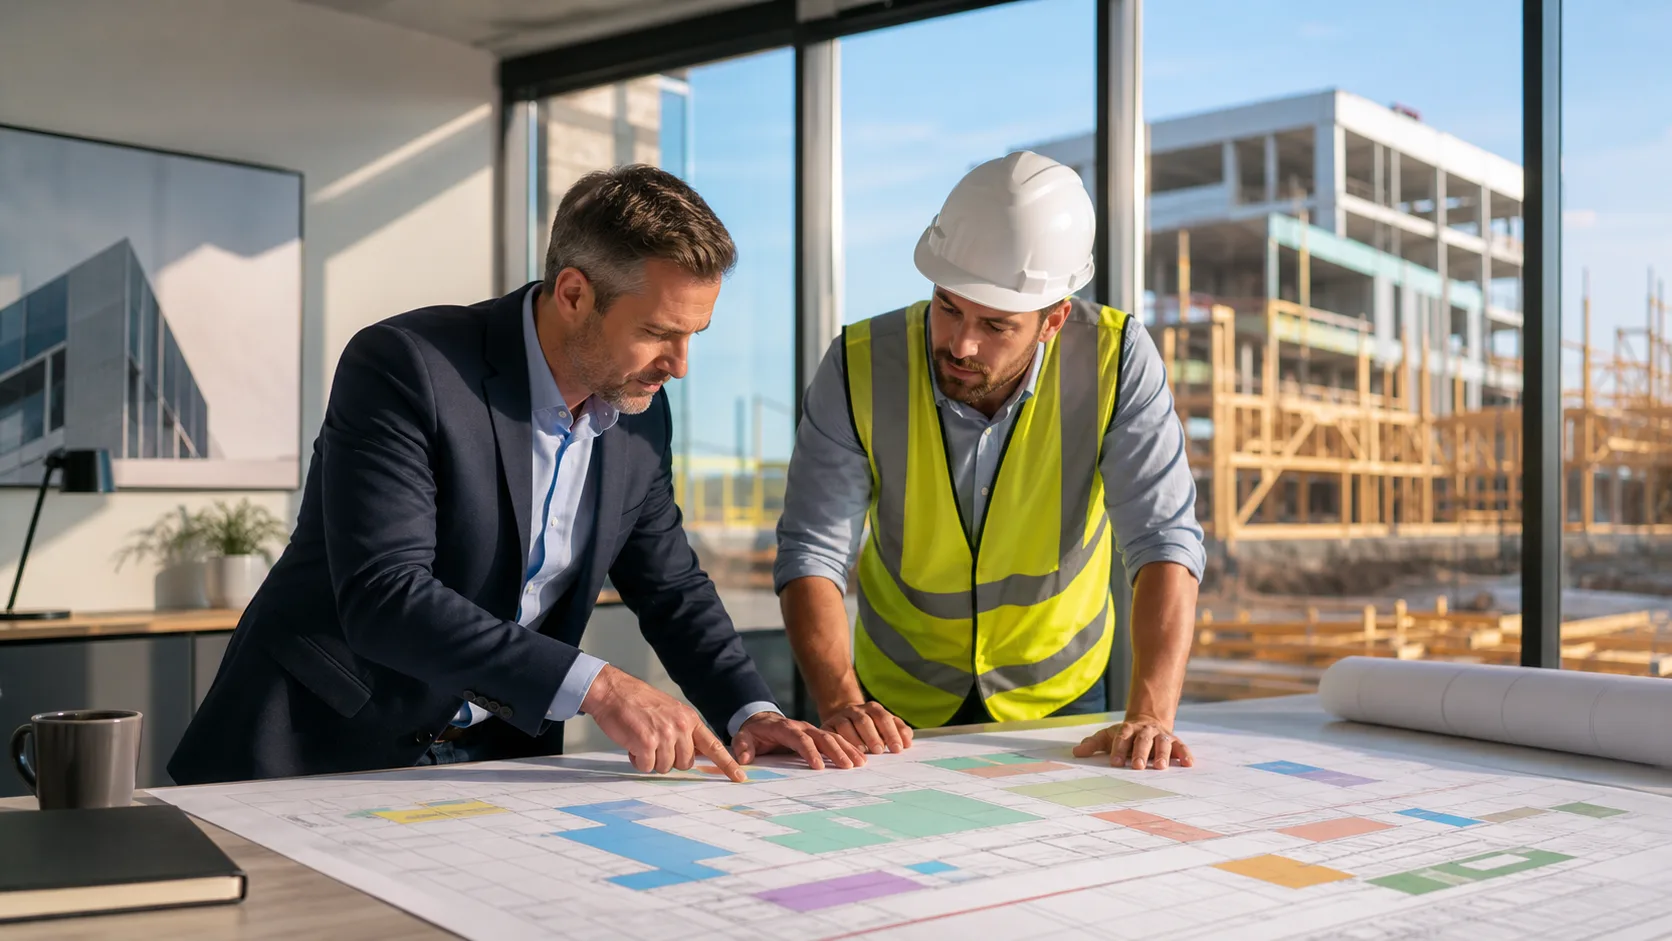
A construction draw schedule for lenders connects your budget, construction milestones, inspections, and payment requests. We use the schedule to confirm that completed work matches the approved scope before additional capital is released. Below, we explain who may qualify, how project costs and value are reviewed, what documents may support draw requests, and which risks to consider before construction begins.
How Construction Draws Protect Your Budget and Who May Qualify
For business-purpose projects, CR Equity AI reviews Construction loan requests only. No, our loans are not for primary residences, owner-occupied homes, or personal-use projects. Eligible borrowers may include real estate investors, business owners, self-employed investors, foreign national investors, ITIN investors, and brokers representing qualified clients.
Before we approve a construction draw schedule, we review the project from several angles. A strong request shows how the property, contractor, budget, and timeline fit together.
- Property location and current ownership or purchase contract
- Construction scope and line-item budget
- Contractor qualifications and agreement
- Estimated completion timeline and projected completed value
- Plans, permits, and other project records requested during underwriting
Eligible ground-up residential investment properties, multifamily properties, and small commercial projects may be considered by CR Equity AI when they meet our underwriting requirements. RV parks, trailer parks, primary residences, and personal-use projects should not be presented as eligible uses.
How Construction Loan Amounts and Draw Access Work
To establish a construction draw schedule, CR Equity AI evaluates the full project budget and property value assumptions. LTC, or loan-to-cost, compares the loan amount with the total project cost. LTV, or loan-to-value, measures the property value against the loan amount.
Your budget needs to account for more than framing, finishes, and labor. Each draw request should connect to an approved category, so gaps in the original budget can create issues later. We may review costs such as land or acquisition expenses, materials, labor, permits, architectural plans, engineering, utility work, inspections, and contingency reserves.
ARV, or after-repair value, estimates what a property may be worth after planned improvements. For ground-up construction, we may instead review the projected completed value. Final loan amounts, draw availability, and property requirements depend on the submitted project and our underwriting review.
How Quickly Construction Draws Can Move
Before closing, CR Equity AI can explain the draw process so you know what evidence to prepare. Draw timing depends on completed work, the quality of your documentation, lender review, and any inspection required for the request.
The usual sequence is straightforward:
- Complete the scheduled construction milestone.
- Submit the draw request with invoices, receipts, or other requested support.
- Provide photographs, contractor updates, and evidence of completed work.
- Complete an inspection if required.
- Receive lender review and an approved draw disbursement.
Seasonal construction planning deserves extra attention. Weather, shorter workdays, material lead times, permit timing, and site conditions can affect your schedule. We recommend building realistic milestones and a contingency plan into the contractor agreement and construction budget before work starts.
How to Control Draw Costs and Project Risks
Before you commit, CR Equity AI should provide a clear explanation of Construction loan costs and conditions. Ask how interest, lender fees, inspection costs, draw administration requirements, extension requests, and unused funds are handled under your specific loan terms.
Construction projects can change quickly, especially when the original plan is incomplete. We often see delays tied to missing permits, unclear contractor bids, unsupported draw requests, change orders, delayed inspections, or labor costs that exceed the initial estimate. A material change to the approved scope, budget, contractor, timeline, or projected value may require additional review before more funds are released.
For a ground-up project, a Construction loan may fit. A Fix & Flip loan may fit an eligible renovation project instead. DSCR measures rental income against the monthly payment. Depending on your investment plan, a Bridge loan, Purchase loan, DSCR Refinance loan, or Small Balance Commercial loan may address a different stage of the property strategy, subject to CR Equity AI underwriting.
Prepare Your Draw Schedule Before Work Begins
At the outset, CR Equity AI can review your business-purpose construction project, contractor plan, budget, and expected draw milestones before you move forward. A complete request gives us a clearer view of whether the project fits the Construction program and which documents may be needed during the draw process.
From the start, keep your approved budget, contractor agreement, invoices, photographs, and change orders organized. Clear records make it easier to show what work has been completed and whether the requested draw matches the original plan.
Plan Draw Requests With Clear Construction Funding Terms
CR Equity AI can help you align your project scope, budget, and disbursement requests before construction begins. Review our construction draw schedule for lenders to understand the Construction program for business-purpose projects. If you need to discuss your property and planned milestones, contact us to speak with our team.
FAQs
Can I Use A Construction Draw Schedule For Ground-Up Work?
Yes. CR Equity AI can use a construction draw schedule for approved ground-up business-purpose projects. The schedule should identify project milestones, the evidence needed for each draw, inspection timing, and contingency handling. Final requirements depend on the property, borrower, contractor, construction scope, budget, and underwriting review.
Does A Lender Release All Construction Funds At Closing?
No. CR Equity AI does not typically release all construction funds at closing for a Construction loan. Approved funds are requested as work progresses under the construction draw schedule. Each draw may require proof of completed work, invoices, receipts, photographs, inspections, or other documents tied to the approved budget.
What Documents Support A Construction Draw Request?
Required draw documents can be identified by CR Equity AI before the first disbursement. Investors commonly prepare a detailed budget, contractor agreement, invoices, receipts, progress photographs, and contractor updates. We may also request lien-related documents or other records based on the property, project scope, draw request, and loan terms.
Can I Change My Construction Budget After Closing?
Yes, but CR Equity AI does not treat budget changes as automatic. Material changes to the construction scope, costs, timeline, contractor, or project value should be reviewed before additional funds are requested. Document change orders early and discuss them before work exceeds the approved construction budget.
How Does A Construction Draw Inspection Work?
A construction draw inspection verifies whether completed work supports the requested disbursement. CR Equity AI can explain whether an inspection is required for your business-purpose project and what the inspection may review. Keep the property accessible and maintain clear records that show the work completed for each scheduled milestone.