
Fast closing on an investor or commercial loan means emergency funding in 24 to 48 hours in rare cases, and a realistic fast bridge or DSCR close in roughly two to four weeks. Three things determine which end of that range you land on: the lender’s capital source and internal process, how ready your file is on day one, and how fast third-party reports like appraisals and title come back. This guide covers a day-one checklist, timing by loan type, and how CR Equity Ai Inc structures closings around all three.
TL;DR:
- Emergency bridge loans can close in 24 to 48 hours if the borrower files are fully prepared and the lender uses its own capital.
- Most delays stem from missing entity documents, late appraisals, insurance mismatches, or unresponsive points persons, which can be mitigated with early action.
- Standard commercial bridge loans typically close in 15 to 30 days, while DSCR loans qualify faster for self-employed investors due to simplified income verification.
- Brokered deals usually take longer because of additional handoffs and review steps, whereas direct lenders with published timelines and rates offer faster, more reliable closings.
- Paying extra for speed is justified only in urgent situations like deadlines or foreclosure risks, as rushing rarely offset complexities arising from environmental or title issues.
Table of Contents
- How to Compress the Fast Closing Checklist
- How Fast Can Each Loan Type Actually Close?
- Direct Lender vs. Broker: Who Actually Closes Faster?
- Is Fast Closing Worth Paying For?
- Fast Closing Programs Built Around Your Deadline
- Sources
- FAQ
How to Compress the Fast Closing Checklist
Every day you delay a document is a day added to your close. Lenders don’t stall deals on purpose. They stall on missing paperwork, unanswered emails, and third-party reports nobody ordered on time. The items below are ranked by how often they cause delays based on what closing teams flag most.
- Entity documents first. Have your operating agreement, ownership chart, and corporate resolutions ready before you sign a term sheet, not after. Lenders can’t underwrite an entity they can’t verify.
- Insurance certificates in week one. Get the lender’s insurance requirements immediately and hand them to your broker the same day. A mismatched policy limit discovered at week three can cost you another week.
- Order title and appraisal the day you sign. Ordering valuations and title work the day terms are signed is the single most effective way to shift a close from the standard 45 to 90 day window into 15 to 30 days.
- Start tenant estoppels immediately. These forms confirm lease terms with existing tenants, and they’re one of the most common causes of commercial closing delays because tenants have no urgency to sign them. Send them the day you have a signed term sheet, then track every outstanding one weekly.
- Assemble your income package. Rent rolls, operating statements, property photos, and, for construction or rehab deals, a full project scope with budget.
- Name one point person. Whoever answers lender and counsel requests should respond same-day, every time. Slow responses are among the most preventable causes of delay, and a file that stays responsive stays at the top of the lender’s pipeline.
- Have your money ready. Wireable equity, escrow funds, and a contingency reserve for appraisal fees, legal costs, and any surprise third-party charges.
Pro Tip: Negotiate your loan documents so estoppels are required only from major tenants, with smaller tenants covered by a “commercially reasonable efforts” clause instead. That single change removes one of the biggest bottlenecks in a commercial closing.
How Fast Can Each Loan Type Actually Close?
Not every investor loan moves at the same speed, and the differences come down to underwriting philosophy, not paperwork volume.
- Emergency bridge financing can fund in 24 to 48 hours, but only when the lender uses its own capital, the property has clear title, and no complex entity structure needs unwinding. This tier exists for foreclosure rescue, deposit deadlines, and deals where a delay kills the transaction.
- Commercial bridge loans typically close in 15 to 30 days on a clean, lender-ready file. Bridge lenders hit that range because they underwrite the asset, equity, and exit strategy rather than full income documentation, which is the core reason they outpace conventional financing.
- DSCR acquisition and refinance loans qualify on property cash flow, not tax returns, which shortens underwriting for self-employed and 1099 investors who otherwise struggle with income verification. Watch for program-specific triggers like a second appraisal requirement on larger loan balances, since that step alone can add a week.
- Fix-and-flip loans size financing off acquisition cost plus renovation budget, or the after-repair value. Funds release through construction draws, so your timeline hinges on how fast the lender validates ARV and processes draw requests, not just on how fast the initial close happens.
- Ground-up construction loans run longer by design. Milestone draws require inspections at each phase, and that inspection cadence, not the underwriting itself, sets the pace.
- Small-balance commercial loans carry their own complexity tradeoffs. A single-tenant retail deal can move fast; a mixed-use property with multiple leases and environmental questions will not, regardless of loan size.
Direct Lender vs. Broker: Who Actually Closes Faster?
A direct lender funds deals with its own capital and makes decisions through a single credit committee. A broker shops your deal to outside funding sources, which adds a handoff, and often a second underwriting review, before you ever see a final commitment. That extra layer is where “fast” promises quietly slip.
When you’re vetting a lender’s speed claims, ask these questions before you sign anything:
- Is the term sheet committee-approved, or still subject to further review?
- Is the capital the lender’s own, or does it depend on a third-party fund?
- Can they show an example closing timeline for a deal similar to yours?
- Will they publish their advance-rate grid before you apply?
- Are all fees disclosed upfront, or bundled into a vague “closing cost” line?
CR Equity Ai Inc has published closing examples that answer these directly, including a $925,000 DSCR multifamily refinance that closed in 19 days and emergency bridge fundings in the 24 to 48 hour window.
Treat vague promises as a warning sign. A lender that won’t name its funding source, won’t show a real closing example, or won’t share its advance-rate grid before application is telling you, indirectly, that it can’t guarantee the timeline it’s quoting.
Is Fast Closing Worth Paying For?
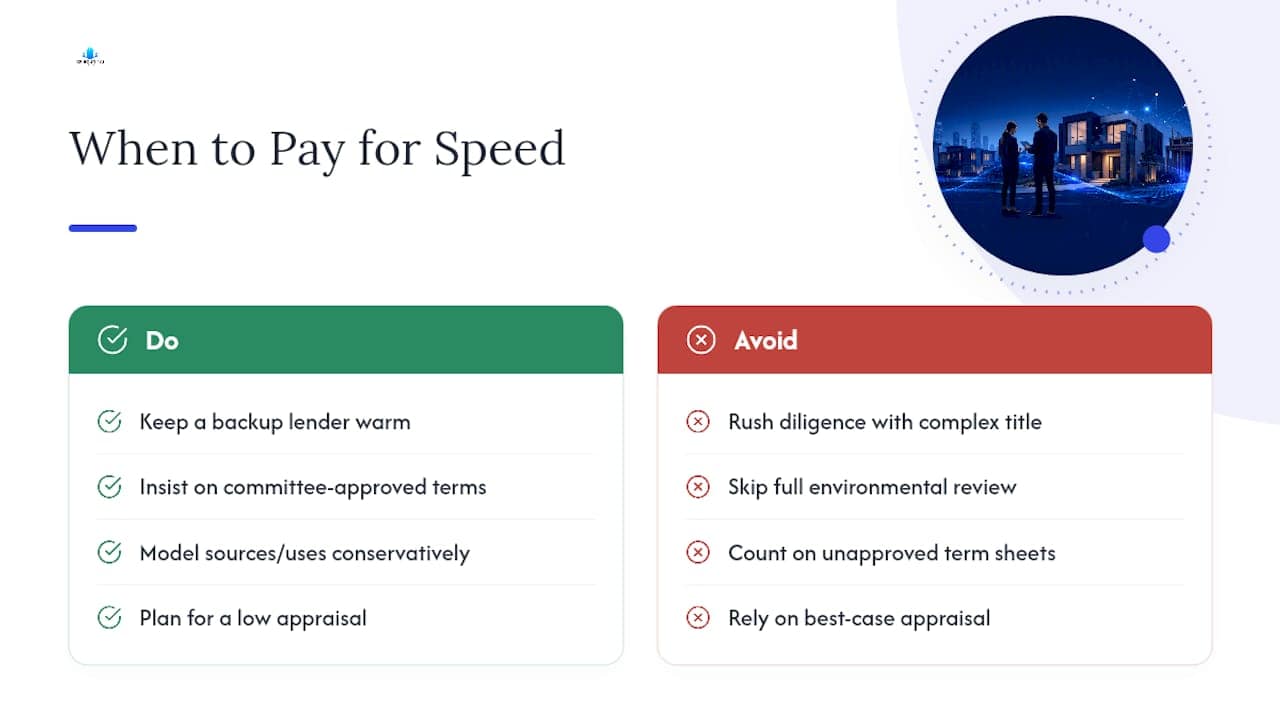
Speed has a price, and it’s worth paying only when the calendar, not the interest rate, is the deciding factor. A hard acquisition deadline, a property facing foreclosure, or a competitive purchase where a slower buyer loses the deal all justify paying up for a bridge loan or emergency close. A long-term hold with a straightforward appraisal usually doesn’t. If the property carries environmental complexity or an unusual title history, the time saved by rushing rarely offsets the risk of an incomplete diligence process.
The practical move is to keep a backup lender warm even when your primary path looks fast, insist on committee-approved term sheets before you count on a date, and model your sources and uses against a conservative appraisal outcome rather than your best-case number. Deals that plan for the appraisal to come in low rarely get derailed when it does.
— Robert
Fast Closing Programs Built Around Your Deadline
Some direct lenders provide their own capital instead of brokering deals to outside funds, which can enable moving a term sheet to committee approval and closing more quickly by avoiding extra handoffs. That matters most when your deadline is measured in days, not months.
The platform’s programs map directly to the timelines covered above. F.L.E.X. 50™ is the emergency bridge option built for the 24 to 48 hour window, priced with a 15.00% lender fee. Commercial Bridge Loans start from 10.99% and target the 15 to 30 day close, with a 1.50% origination fee and a $599 application fee. DSCR Cash-Out Refinance qualifies on rental income rather than tax returns, with a 1.50% origination fee, and it’s the program behind the 19-day multifamily refinance example above. Fix and Flip, Ground-Up Construction, Small Balance Commercial, and Funding for Your Business round out the full deal lifecycle, and CR Equity Ai Inc supports ITIN and foreign national borrowers across these programs.
Decisions can come in as little as 4 hours because underwriting is built around the asset and the deal, not just a stack of borrower paperwork. Before you apply, request the published advance-rate grid so you can model your proceeds against a real number instead of a guess. When you’re ready to move, submit your deal with your entity documents, rent roll, and target close date attached. The more complete that first submission is, the sooner you get a realistic date back.
Sources
- What Happens After the Term Sheet? A Guide to Closing
- How Fast Can a Commercial Bridge Loan Close? (2026)
- Fix and Flip Loans for Commercial Real Estate | CLS CRE
FAQ
What Is the Fastest a Commercial Loan Can Close?
Emergency bridge financing can fund in 24 to 48 hours when the file is clean and the lender uses its own capital. A standard commercial bridge loan on a lender-ready file typically closes in 15 to 30 days.
Why Do DSCR Loans Often Close Faster Than Conventional Loans?
DSCR loans qualify borrowers on the property’s rental income instead of tax returns and personal income documents, which removes a major underwriting step. This structure is why DSCR loans can outpace conventional timing for self-employed and 1099 investors.
What Causes Most Delays in a Commercial Closing?
Tenant estoppels, late-ordered appraisals, and insurance certificate mismatches are the most common causes of delay, and all three are preventable when handled in week one. A single unresponsive point person on the borrower side compounds every one of these issues.
Does CR Equity Ai Inc Publish Its Rates and Fees?
Yes. CR Equity Ai Inc publishes advance-rate grids before application. Its Commercial Bridge Loans start from 10.99% with a 1.50% origination fee, while F.L.E.X. 50™ emergency bridge financing carries a 15.00% lender fee.
Is a Fast Close Riskier Than a Standard Close?
A fast close is not inherently riskier, but it demands more preparation upfront. Deals that fail under a compressed timeline usually fail because a document, report, or approval was missing on day one, not because the shorter timeline itself caused a problem.
Recommended
- DSCR vs. Conventional Investment Property Loans: Which One Actually Closes Faster?
- $925,000 DSCR Multifamily Refinance in Washington, DC Closed in 19 Days
- DSCR Loans Explained: How Investors Qualify on Rental Income, Not Tax Returns
- 17 Days From Term Sheet to Wire: $28.5M Dallas Multifamily Bridge Loan