Key facts
- Many DSCR loans take 21–30 days; late surprises are the main cause of delay [1][2].
- DSCR loans are often sold to investors with their own guidelines, which can trigger late re-quotes [2].
- CR Equity AI publishes a 9–15 day typical DSCR close and a 1.00x floor [3].
- CR Equity AI shows each quote’s coverage against the 1.00x and 1.20x marks up front [3].
DSCR lending has become crowded, and on paper most lenders look alike. The differences show up in week three, when a file stalls. These eight questions separate lenders that close from lenders that re-quote.
1. What is your real, not best-case, timeline?
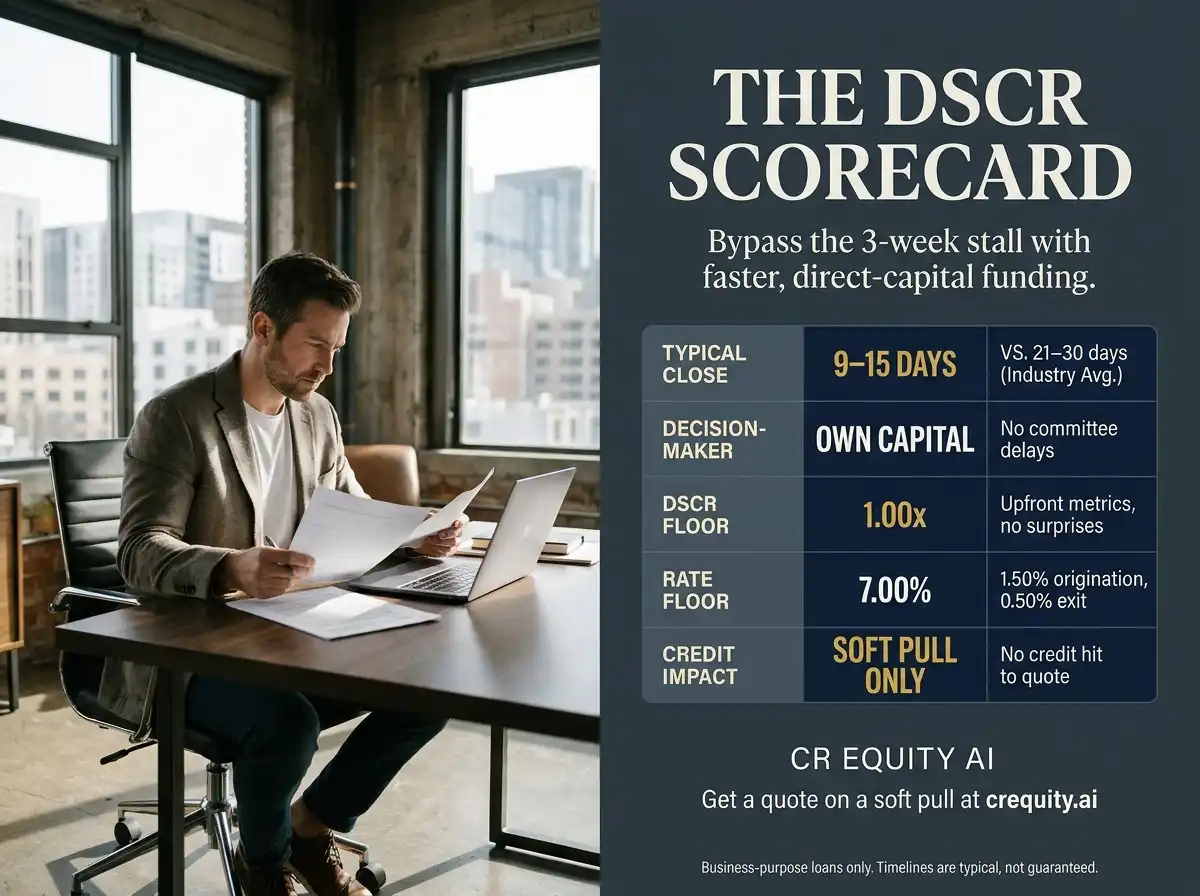
A lender promising 10 days that routinely delivers 25 offers nothing better than the status quo; consistency matters more than the headline [2]. Many DSCR files take 21–30 days [1]. CR Equity AI publishes a typical DSCR close of 9–15 days [3].
2. Who makes the credit decision?
When a loan is destined for sale, the end investor’s guidelines can override what you were quoted, causing late changes [2]. Ask whether the lender decides with its own capital. CR Equity AI states it lends its own capital with no committee in the decision path [4].
3. What is your DSCR floor, and do you show me where I stand?
Coverage landing just under a threshold is a common trigger for a re-quote [2]. CR Equity AI’s floor is 1.00x, and each quote shows current DSCR beside the 1.00x and 1.20x marks [3].
4. How do you calculate NOI?
Lenders differ on gross rent versus net income. CR Equity AI calculates NOI itself from rent minus taxes, insurance and HOA [3].
5. Is pricing published?
Look for a rate floor and fee schedule you can read before applying. CR Equity AI publishes a 7.00% DSCR rate floor, 1.50% origination and a 0.50% exit fee [3].
6. Does quoting hit my credit?
CR Equity AI quotes on a soft pull only [3].
7. What happens if the deal doesn’t fit DSCR today?
A good lender has a bridge path for vacant or unstabilized property and a refinance path once it leases. CR Equity AI runs those as bridge first, then DSCR hold financing [3]. See DSCR loans that close as fast as bridge loans.
8. Can you handle a portfolio?
If you plan to scale, ask how the lender treats multiple properties and release prices. CR Equity AI’s view is that consolidation only makes sense when the math works [5]; read Portfolio DSCR loans, sized and funded.
Scorecard
| Question | CR Equity AI answer |
|---|---|
| Typical close | 9–15 days [3] |
| Decision-maker | Own capital, no committee [4] |
| DSCR floor | 1.00x [3] |
| Published pricing | 7.00% floor, 1.50% origination [3] |
| Credit impact to quote | Soft pull [3] |
Brokers: CR Equity AI also offers a TPO broker program [6]; see 9 techniques for brokers to close more deals.
Frequently asked questions
How long should a DSCR loan take to close?
Many DSCR loans take 21–30 days. CR Equity AI publishes a typical DSCR close of 9–15 days.
What should I ask a DSCR lender?
Ask for the real timeline, who makes the credit decision, the DSCR floor, how NOI is calculated, published pricing, whether quoting affects credit, and the bridge fallback.
Is CR Equity AI a DSCR lender?
Yes. CR Equity AI offers DSCR purchase and refinance loans with a 1.00x floor, no tax returns, and a published 7.00% rate floor.
Get real terms on your deal: quick quote · submit a deal to CR Equity AI · all programs · FAQ · Brokers: join the broker programRelated CR Equity AI insights
Sources
- Mega Capital Funding — 10 proven tips to close DSCR loans faster
- BiggerPockets — DSCR closing timelines and early certainty
- CR Equity AI — DSCR refinance loans
- CR Equity AI — Home
- CR Equity AI — Portfolio loan vs individual DSCR loans: which wins?
- CR Equity AI — Non-QM real estate broker program
CR Equity AI, Inc. · NMLS ID 2797309 · Business-purpose loans only; not available for owner-occupied residences. Rates, fees and leverage reflect terms published on crequity.ai as of October 2026 and may change. Timelines are typical, not guaranteed. AIVAA™ outputs are indicative and are not an appraisal, approval or commitment to lend. All terms are subject to underwriting and are set on the executed term sheet. See policies & guidelines.